Within the ever-evolving panorama of personal finance, one niche that has emerged primarily throughout financial downturns is the payday loan business, especially for those with bad credit. This observational research article goals to delve into the world of bad credit payday loans supplied by direct lenders, investigating their accessibility, the implications for borrowers, and the experiences people face when using these financial merchandise.
Background
Payday loans are brief-term monetary solutions designed to offer fast money, typically due on the borrower’s subsequent payday. These loans typically include excessive-interest rates and charges, particularly for borrowers with bad credit. Observations reveal that many consumers turn to those loans throughout emergencies or financial crises when entry to more conventional types of credit score is unavailable, thus illuminating the intersection between urgency and financial desperation.
The Accessibility of Bad Credit Payday Loans
From observational findings, it is clear that direct lenders have simplified the borrowing process, enabling quicker entry to payday loans. Many direct lending establishments have established a minimal barrier for entry, typically requiring only proof of earnings, a sound checking account, and identification. This ease of access attracts these with poor credit histories, who could really feel ostracized by conventional lenders that always examine credit score scores and impose stringent necessities.
Moreover, online platforms have proliferated, allowing borrowers to use for payday loans from the comfort of their properties. It was noted throughout the analysis that many individuals most popular this anonymity, bypassing the judgment they feared from conventional financial establishments. However, this comfort came at a value, because the repayment phrases typically included exorbitant curiosity rates and charges, compounding the monetary burden for borrowers.
The Borrower Experience
A significant statement involved interviewing individuals who had beforehand used bad credit payday loans. Many expressed emotions of vulnerability and desperation when searching for these loans, typically driven by sudden monetary emergencies like medical payments or car repairs. If you have any concerns about the place and how to use Body Positivity provider guide, you can contact us at our page. Borrowers reported that the preliminary technique of obtaining these loans was quick and uncomplicated, usually accomplished within lower than an hour. This speed was seen as a double-edged sword; while useful in dire conditions, it also led to poorly-informed choices concerning repayment and financial planning.
Some borrowers recounted experiences of rolling over loans, the place they would take out a new loan to pay off the earlier one, leading to a cycle of debt that became increasingly troublesome to escape. Whereas direct lenders marketed these loans as brief-time period options, many borrowers ended up in lengthy-term monetary distress. This statement correlates with research that point out excessive charges of delinquency and default amongst payday loan borrowers, emphasizing the need for larger monetary literacy and consciousness relating to the long-time period implications of those loans.
The Monetary Influence
The monetary repercussions of bad credit payday loans are severe and multi-dimensional. Analyzing circumstances the place people took out multiple payday loans revealed alarming patterns. Borrowers typically succumbed to an unrelenting cycle of debt, wherein excessive-interest rates led to charges and penalties that exceeded the original loan quantity. Observatories famous that this cycle often diverted funds that might have been used for essential expenses reminiscent of groceries or rent, resulting in additional financial pressure and anxiety.
Additionally, a big number of borrowers reported that this reliance on payday loans adversely affected their overall credit score scores. Regardless of being unable to secure conventional loans, the consecutive failures in repaying payday loans contributed to a deteriorating credit profile. Thus, while these loans served as immediate relief, they had long-lasting results on the person's monetary health and stability.
Consumer Consciousness and Regulation
One space of concern is the overall lack of consciousness surrounding the realities of payday loans, notably for borrowers with dangerous credit. Observational findings indicated that many individuals were not absolutely informed of the interest rates and repayment agreements earlier than signing contracts. In several circumstances, borrowers expressed confusion about the overall amount owed after interest and charges were added, revealing a disconnect between lender communications and borrower comprehension.
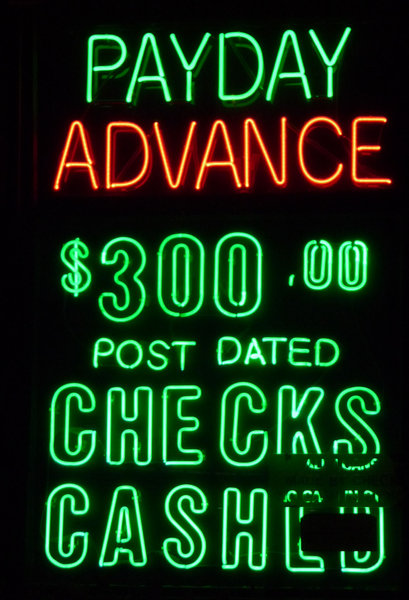
Laws surrounding payday lending have been sluggish to keep tempo with the rise of direct lenders, creating an environment the place predatory lending practices can thrive. Conversations with shopper advocacy teams revealed a urgent need for tighter laws that may protect susceptible populations from exploitative practices. Initiatives aimed at improving transparency and borrower schooling are critical in serving to consumers make knowledgeable monetary decisions.
Conclusion
The observational analysis outlined in this text sheds light on the complicated realities of bad credit payday loans from direct lenders. Whereas these loans provide rapid monetary relief for borrowers in need, they usually come bundled with high prices and long-term consequences that may lead to a vicious cycle of debt. There is an important want for increased consumer awareness, better regulations, and more responsible lending practices to ensure that those with unhealthy credit don't fall prey to exploitative monetary merchandise. Because the payday loan business continues to evolve, the responsibility lies with each lenders and borrowers to foster a more knowledgeable and sustainable method to brief-term lending.